France’s borrowing costs have climbed to levels not seen in a generation, and the warning signs are no longer confined to trading screens. Deutsche Bank chief executive Christian Sewing has described the country’s fiscal and political turmoil as concerning, saying the bond market is “not lying.” His intervention came as the yield on France’s benchmark 10-year government debt briefly rose above 5 percent for the first time since 2002, a milestone that has sharpened questions about whether Paris can restore fiscal credibility before next year’s presidential election.
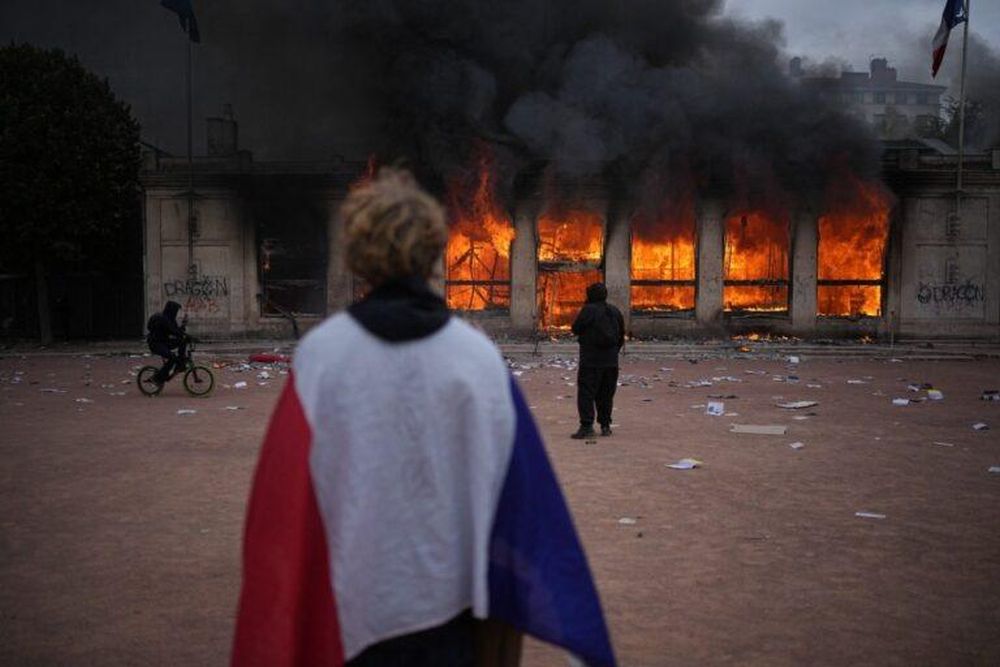
The immediate trigger is a collision between public anger and budget arithmetic. More than half a million people marched against school underfunding and the rising cost of living, but some demonstrations descended into looting and violence, leading to more than 2,300 arrests. At the same time, Prime Minister Sébastien Lecornu’s government is trying to push a 2027 budget through a fragmented parliament, with Finance Minister Roland Lescure signaling that spending cuts could be forced through if lawmakers refuse to approve them. That approach may reassure investors, yet it risks inflaming the very unrest that has already unsettled markets.
The numbers explain why investors are uneasy. France’s public debt is roughly 120 percent of gross domestic product, while its deficit remains well above the European Union’s preferred threshold. The gap between French and German borrowing costs widened to around 157 basis points, close to levels last seen during the eurozone debt crisis, effectively charging Paris a rising premium for its political uncertainty. Sewing stopped short of calling it a debt crisis, but framed it as a wake-up call for public finances across Europe, arguing that disciplined budgets and controlled debt are essential.
The deeper problem is that fiscal repair and electoral politics are moving in opposite directions. With the presidential vote less than six months away, leading candidates from the far right and hard left have promised to lower the retirement age from 64 to 62, a pledge that would add pressure to public finances rather than relieve it. Markets may remain volatile until voters deliver a clearer mandate, and until then France faces a difficult test: convincing lenders that it can cut spending without triggering a broader political backlash.
#France #DeutscheBank #ChristianSewing #BondMarket #FrenchDebt #Eurozone #PublicFinance #EuropeanEconomy #PoliticalRisk #PresidentialElection