Uber Technologies shares have slipped to a fresh 52-week low just days before the company reports quarterly results, and the timing has turned an otherwise routine earnings release into a test of investor confidence. The stock has fallen sharply over the past year, leaving shareholders to question whether the platform can sustain growth while competition intensifies across ride-hailing, food delivery, and autonomous transportation. The central concern is not simply one weak quarter. It is whether Uber can preserve its role as the essential marketplace connecting riders, drivers, couriers, restaurants, and merchants.
The immediate catalyst appears to be a potential shift in the delivery landscape. Reports that DoorDash may pursue a major acquisition of Instacart have revived fears that Uber could face a more consolidated and better-capitalized group of rivals in grocery and local commerce. If Instacart’s discussions with Uber are no longer active, Uber may lose an opportunity to deepen its grocery presence at a moment when rivals are seeking scale. Investors are asking whether Uber’s delivery business can continue expanding without relying on costly partnerships or acquisitions.
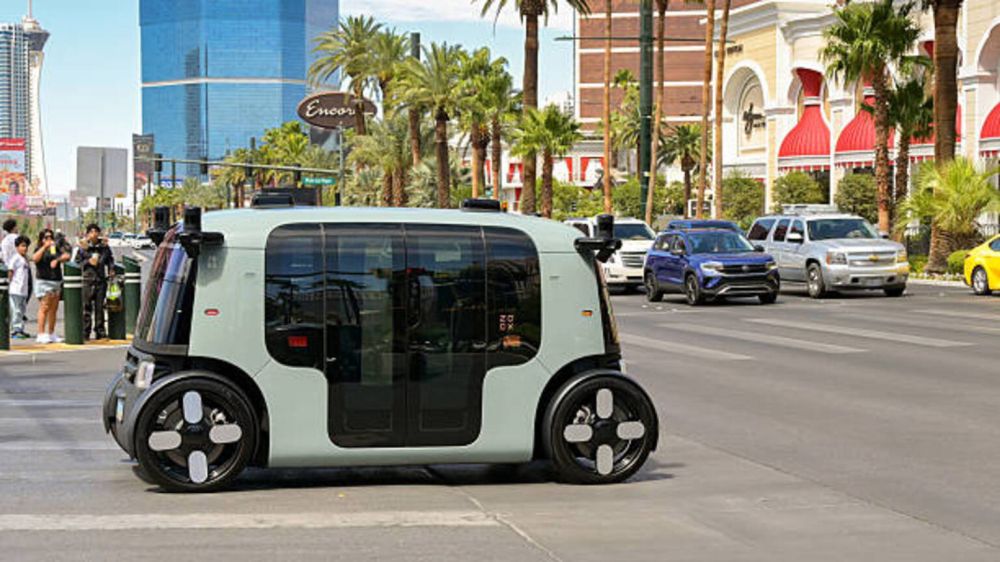
Autonomous vehicles add another layer of uncertainty. Waymo, Zoox, and Tesla each operate or are developing their own transportation services, raising a difficult strategic question: will the companies building robotaxis continue to rely on Uber’s demand network, or will they eventually bypass it? Uber has positioned itself as a distribution platform for autonomous fleets, but the market wants evidence that this arrangement will create durable economics rather than hand valuable customer relationships to technology companies. Until that evidence becomes clearer, every advance in self-driving technology can be read as a potential threat to Uber’s core business.
Attention now turns to the earnings report expected before the market opens on November 4. Analysts are looking for revenue near $14.67 billion and adjusted earnings of $0.86 per share, while management has guided toward earnings between $0.84 and $0.88 per share. Options markets imply a move of roughly 6.8% in either direction after the release. Yet Wall Street remains broadly constructive, with most analysts rating the stock favorably and an average price target well above recent trading levels. The disconnect is striking: many analysts see value, while the market is pricing in structural risk. Uber’s next results will need to do more than meet estimates. They will need to reassure investors that its marketplace still matters in a rapidly changing transportation economy.
#Uber #StockMarket #Earnings #Investing #Robotaxis #DoorDash #Instacart #TechStocks #RideHailing #Delivery #MarketAnalysis